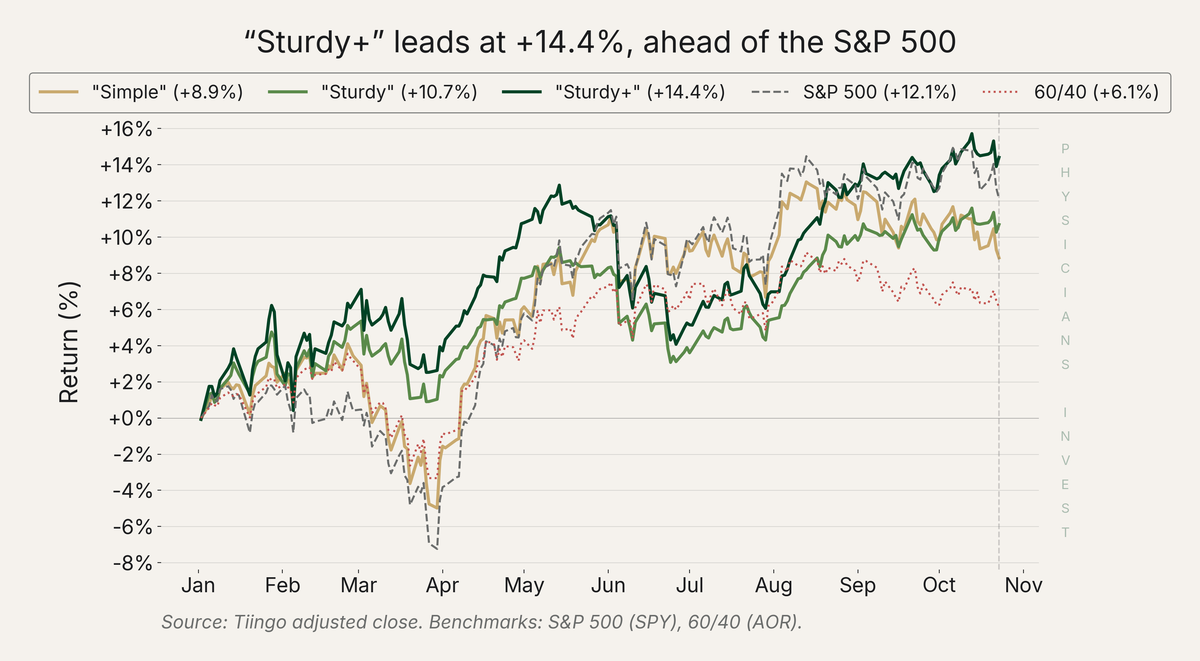
Year to date, our three hypothetical model portfolios are up between 8.9% and 14.4%, versus 12.1% for the S&P 500 for comparison. This month we ran our first quarterly drift check to see if anything needs to be rebalanced. Simple stayed inside its bands and does not change. Sturdy and Sturdy+ both need to be reset to their target weights.
The 2-Minute Version
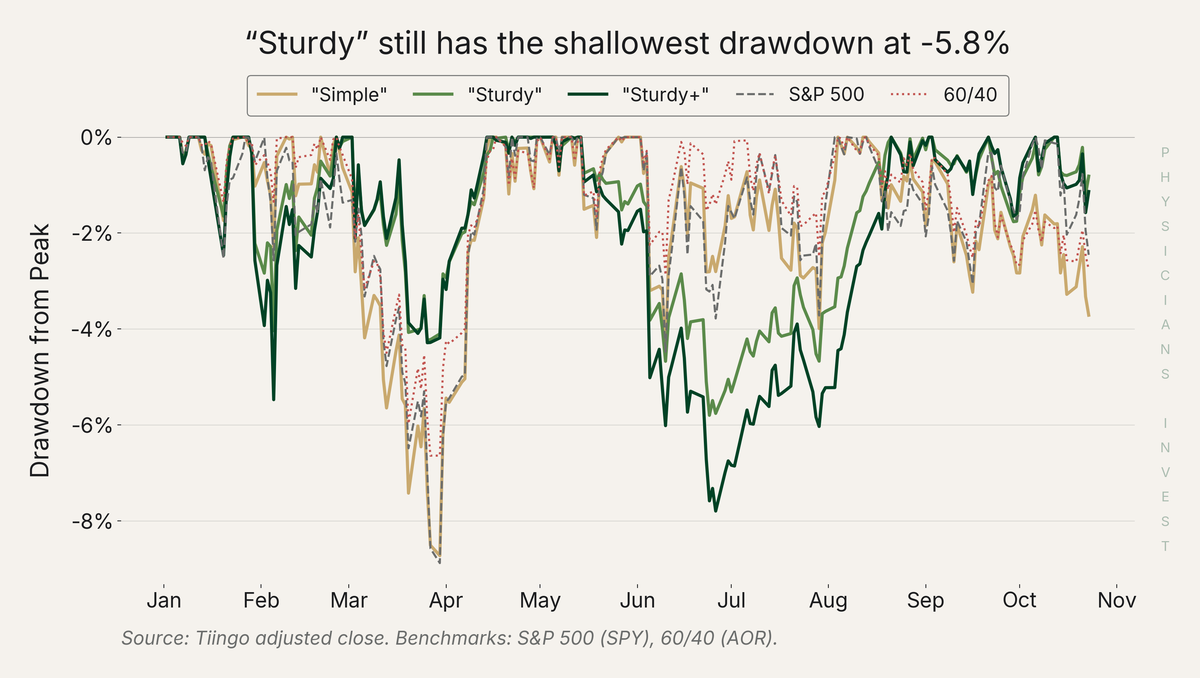
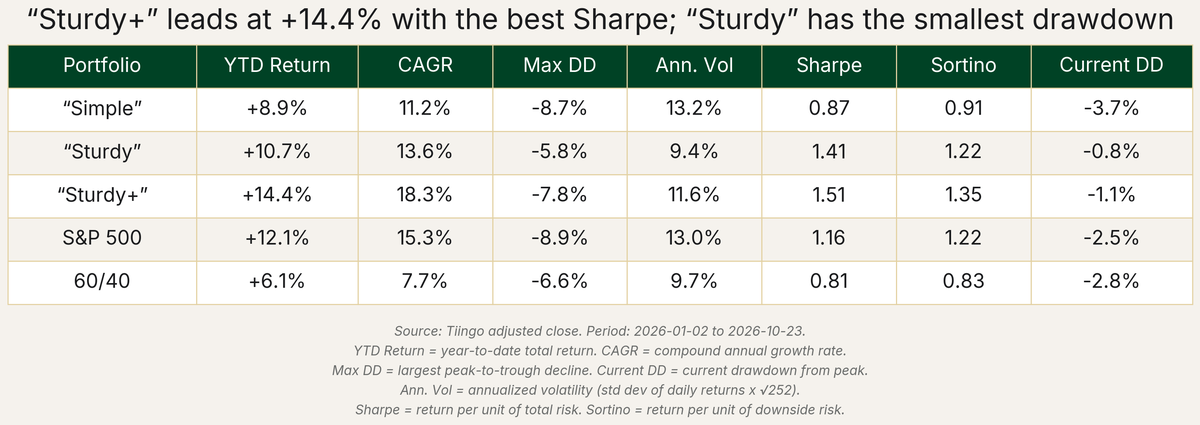
- Best return: Sturdy+ leads at +14.4% YTD, ahead of the S&P 500's +12.1% for comparison, with the best risk-adjusted return of the three (Sharpe of 1.51, Sharpe Ratio is a measure of return per unit of risk).
- Lowest drawdown: Sturdy has had the smoothest ride. Its worst drawdown (its biggest peak-to-trough drop) is still -5.8%, versus -8.9% for the S&P 500. It gained 0.4% since our September update and sits at +10.7% YTD.
- Easiest to manage: Simple fell 2.8% since our September update as international stocks dropped. It sits at +8.9% YTD. No changes.
- Rebalance actions: XLE breached its rebalancing band in Sturdy and Sturdy+, so both reset to target weights. In a taxable account, a trim like this creates a short-term gain. Details below.
Market Context
Since our September update, the Fed raised its short-term rate on September 16, its first hike since 2023, to a range of 3.75-4.00%. The 10-year Treasury yield climbed from 4.80% in early September to 5.31% on October 5, its high for the year. Recently, on October 22, stocks sold off on worries about AI spending and the 10-year yield fell below 5% in its biggest one-day drop in more than two years, as investors moved their capital into Treasuries as a safe haven.
Oil is back above $100. The spot price of West Texas crude dipped to $85 in late September, then jumped as Iran escalated attacks around the Strait of Hormuz and reached $110 on October 19.
This month shows why the models hold more than the S&P 500. Since September the S&P 500 slipped 0.5% while Sturdy+ gained 1.1% and Sturdy gained 0.4%.
How We Rebalance
When we launched these models in April, we said we would make small tweaks monthly and bigger rebalances quarterly. Here is the rule we use:
- Check once a quarter, in the January, April, July, and October issues.
- Trade only when a holding drifts outside its band. A holding with a target of 20% or more gets rebalanced if it drifts 5 percentage points from target. A smaller holding gets rebalanced if it drifts 25% of its own target. A 10% target, for example, triggers below 7.5% or above 12.5%.
- If any holding breaks its band, the whole portfolio resets to target.
This is often called the 5/25 rule. It keeps a winner from taking over the portfolio without trading every time markets wiggle.
A note on taxes. Every position trimmed this month dates from January 2, 2026, so in a taxable account the trim is a short-term gain, taxed as ordinary income. Inside a 401(k), 403(b), or IRA, a rebalance has no tax cost. Taxable investors often rebalance by directing new contributions to the underweight holdings, or wait until the original lots turn long-term after January 2, 2027. (New purchases start their own one-year clock.)
Performance Dashboard
 Source: Physicians Invest model portfolio. Hypothetical $100K, not actual returns.
1. "Simple" Portfolio
For: Residents and early-career physicians who want a "set it and forget it" approach.
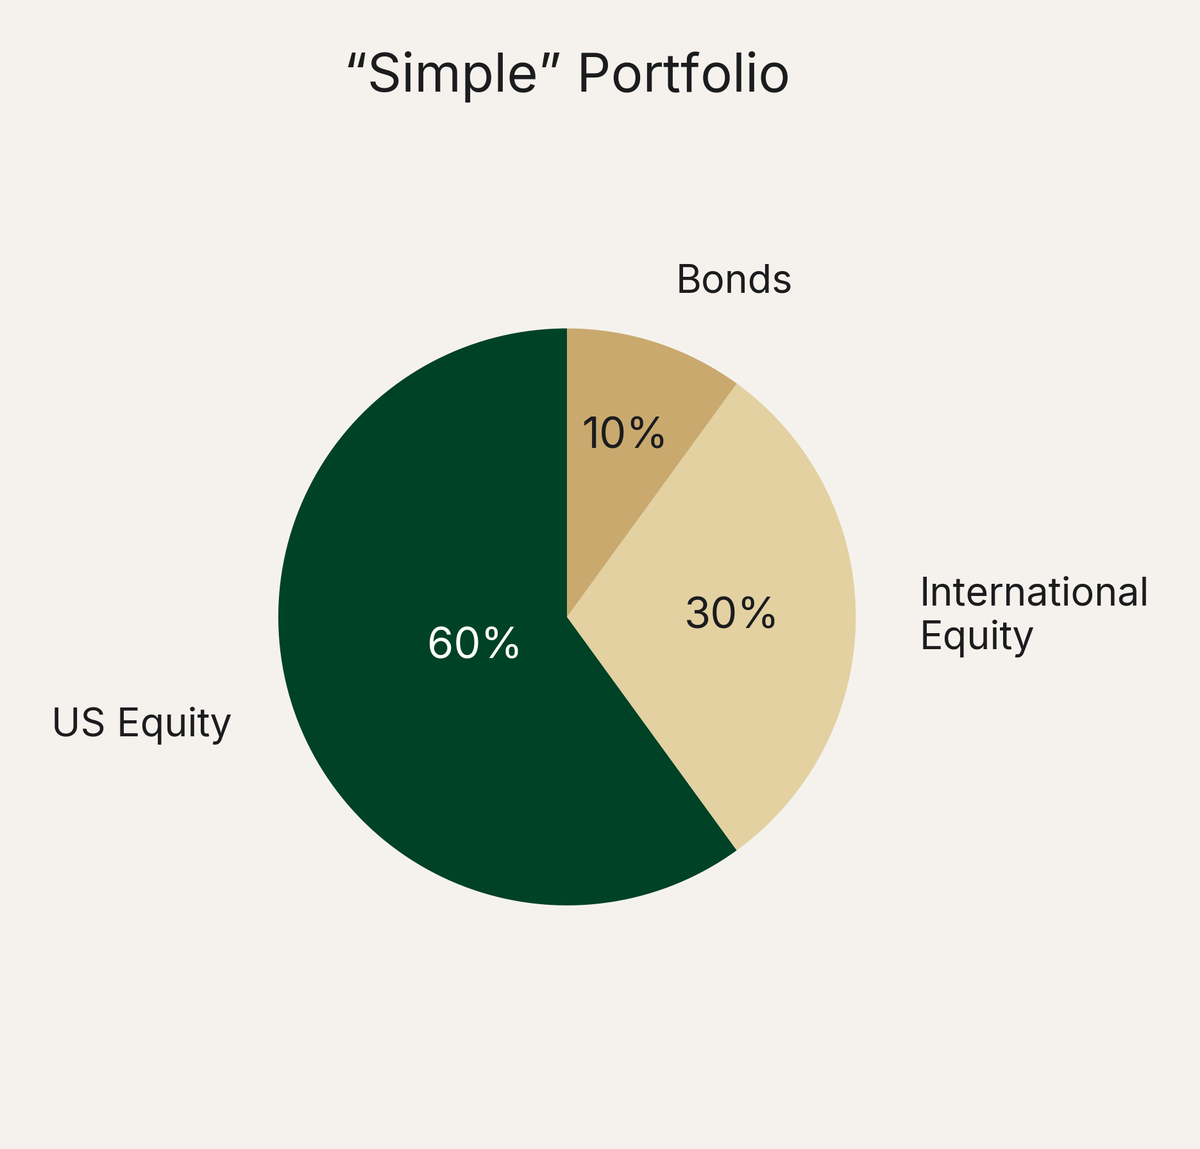
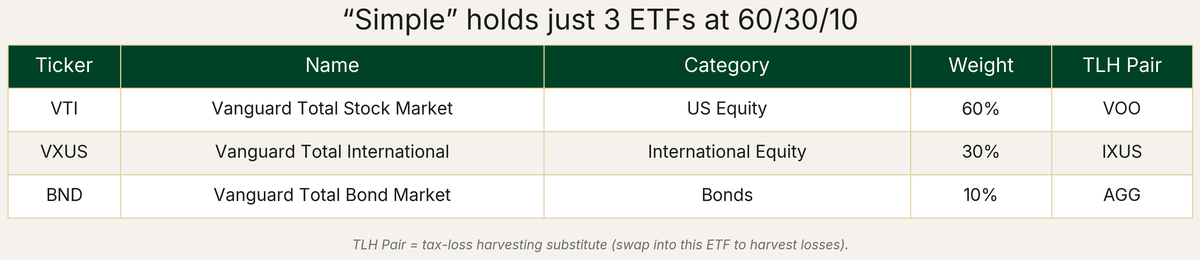
Strategy: Three ETFs at 60/30/10. Beauty in simplicity.
Advantages: Lowest expense ratios in the lineup (under 0.05% blended; expense ratio is the annual fee an ETF charges, expressed as a percent of assets). Easy to rebalance with three line items. No exotic holdings.
Disadvantages: Concentrated in stocks and bonds. When both go down together (like Q1 2026), there is nowhere to hide. Diversifies across assets but does not perform well when interest rates are increasing (2022).
Tax-Advantaged Tweak: In a Roth or 401(k), investors who want real-estate exposure could add a 5-10% REIT (real estate investment trust) slice carved from US equity (VNQ is one common ETF to use for this). REITs throw off ordinary income that gets taxed at the marginal rate in a taxable account so REITs are typically held in tax-protected accounts.
What Changed
No changes this month. Simple passed its quarterly drift check: VTI sits at 61.3% against a 60% target, VXUS at 29.8% against 30%, and BND at 8.9% against 10%. All three are inside their bands. Since our September update, US stocks (VTI) slipped 1%, international stocks (VXUS) fell 6%, and bonds (BND) were about flat. Net, -2.8% and +8.9% YTD.
Tax Loss Harvesting Opportunities
One holding is underwater:
- BND (Total Bond Market): started the year at $73.32, now about $71.20, roughly 3% lower. The tax-loss harvesting substitute is AGG. At about 3%, the loss is small enough that a harvest may not be worth the trouble yet.
Refresher: tax-loss harvesting means selling at a loss to offset gains (or up to $3,000 of ordinary income a year), then buying a near-identical fund to stay invested. Buying the same or a substantially identical fund within 30 days before or after the sale, in any account, defers the loss (the wash-sale rule).
2. "Sturdy" Portfolio
For: Mid-career attendings who want a smoother ride without giving up return.
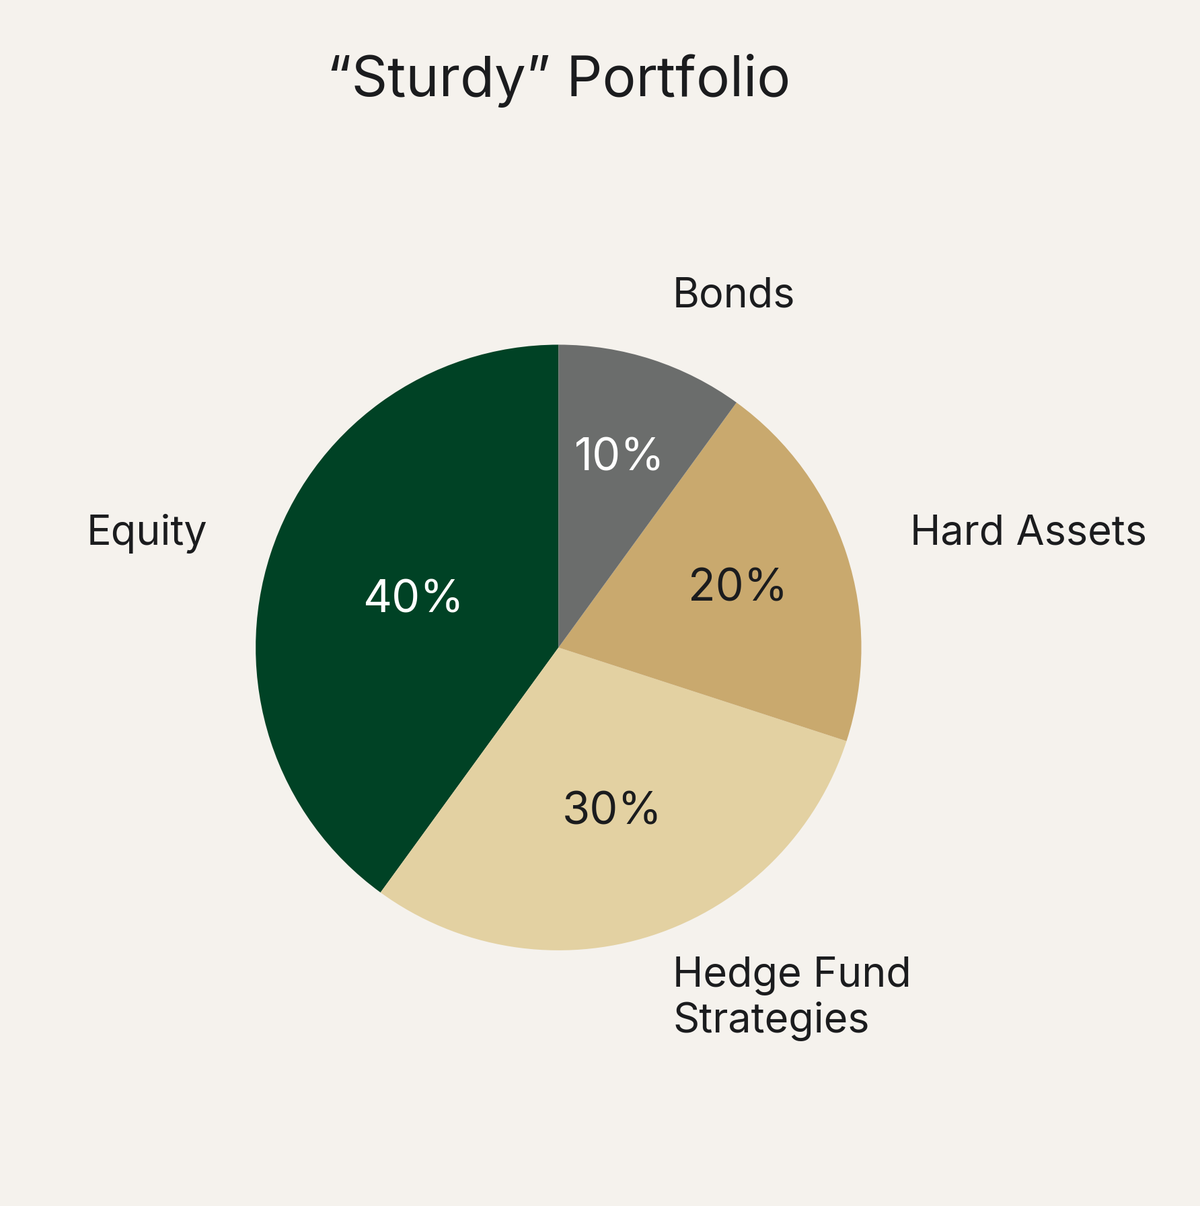
Strategy: 40% equity / 30% hedge fund strategies / 20% hard assets / 10% bonds.
Advantages: Lower volatility for the same long-term performance as Simple. Diversifies risk exposures into other risk assets along with stocks.
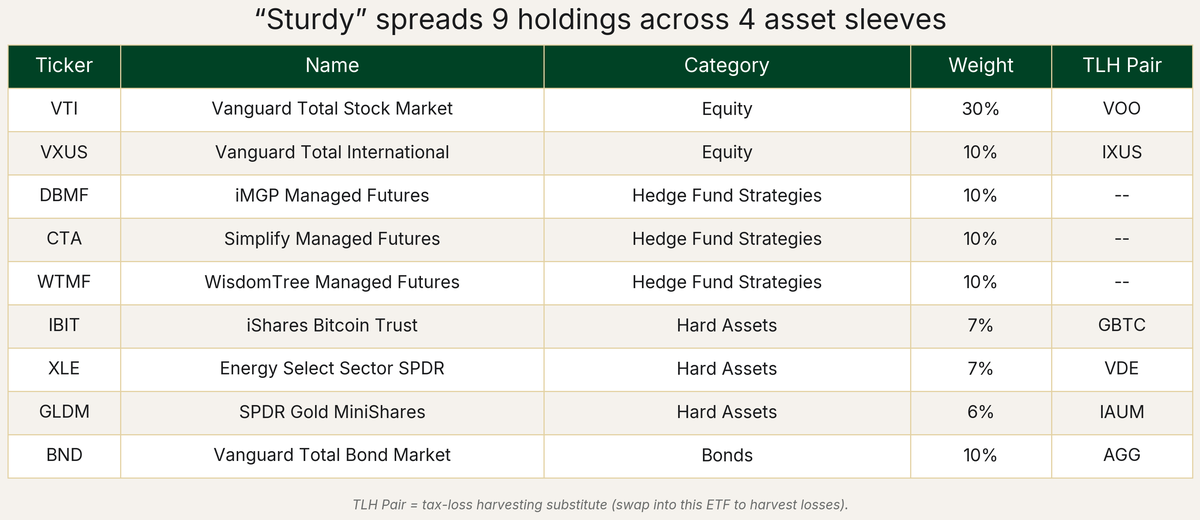
Disadvantages: Nine holdings means more rebalancing complexity than Simple. Hedge fund ETFs have higher expense ratios (0.65-0.85%) than the equity holdings and take more homework to understand: what they are doing under the hood, how they make money, and when they pay off.
Tax-Advantaged Tweak: Asset location is the practice of placing tax-inefficient holdings in tax-sheltered accounts. Investors applying asset location here would typically place more BND, GLDM, WTMF, CTA, and DBMF exposure in tax-sheltered accounts, keeping more index fund exposure (VTI, VXUS, XLE, IBIT) in taxable brokerage accounts.
What Changed
Rebalanced to target. XLE had grown to 9.7% of Sturdy against a 7% target, 38% over and past its 25% band. Per the rule, the whole portfolio reset to target at the October 23 close. The main trades, as a share of the portfolio:
- Trimmed XLE (9.7% to 7%), DBMF (10.5% to 10%), and CTA (10.4% to 10%)
- Added to IBIT (5.7% to 7%), BND (8.8% to 10%), and GLDM (5.0% to 6%)
Holdings and targets are unchanged. The model sold some of what ran and bought some of what lagged, which is the point of rebalancing.
Tax Loss Harvesting Opportunities
- IBIT (iShares Bitcoin Trust): started the year at $50.94, now about $45.96, an unrealized loss of about 10%. The substitute is GBTC.
- GLDM (SPDR Gold MiniShares): started the year at $85.74, now about $79.13, down about 8%. The substitute is IAUM.
- BND (Total Bond Market): down about 3%. The substitute is AGG. As in Simple, the loss is small for now.
The rebalance adds to IBIT, GLDM, and BND, the same three holdings on the harvest list. Because the wash-sale window runs 30 days both ways, some investors who plan to harvest make the rebalance purchase in the substitute (GBTC, IAUM, or AGG) instead.
3. "Sturdy+" Portfolio
For: Sophisticated investors comfortable with leveraged ETF mechanics, looking for higher long-term returns than the market and willing to take on volatility.
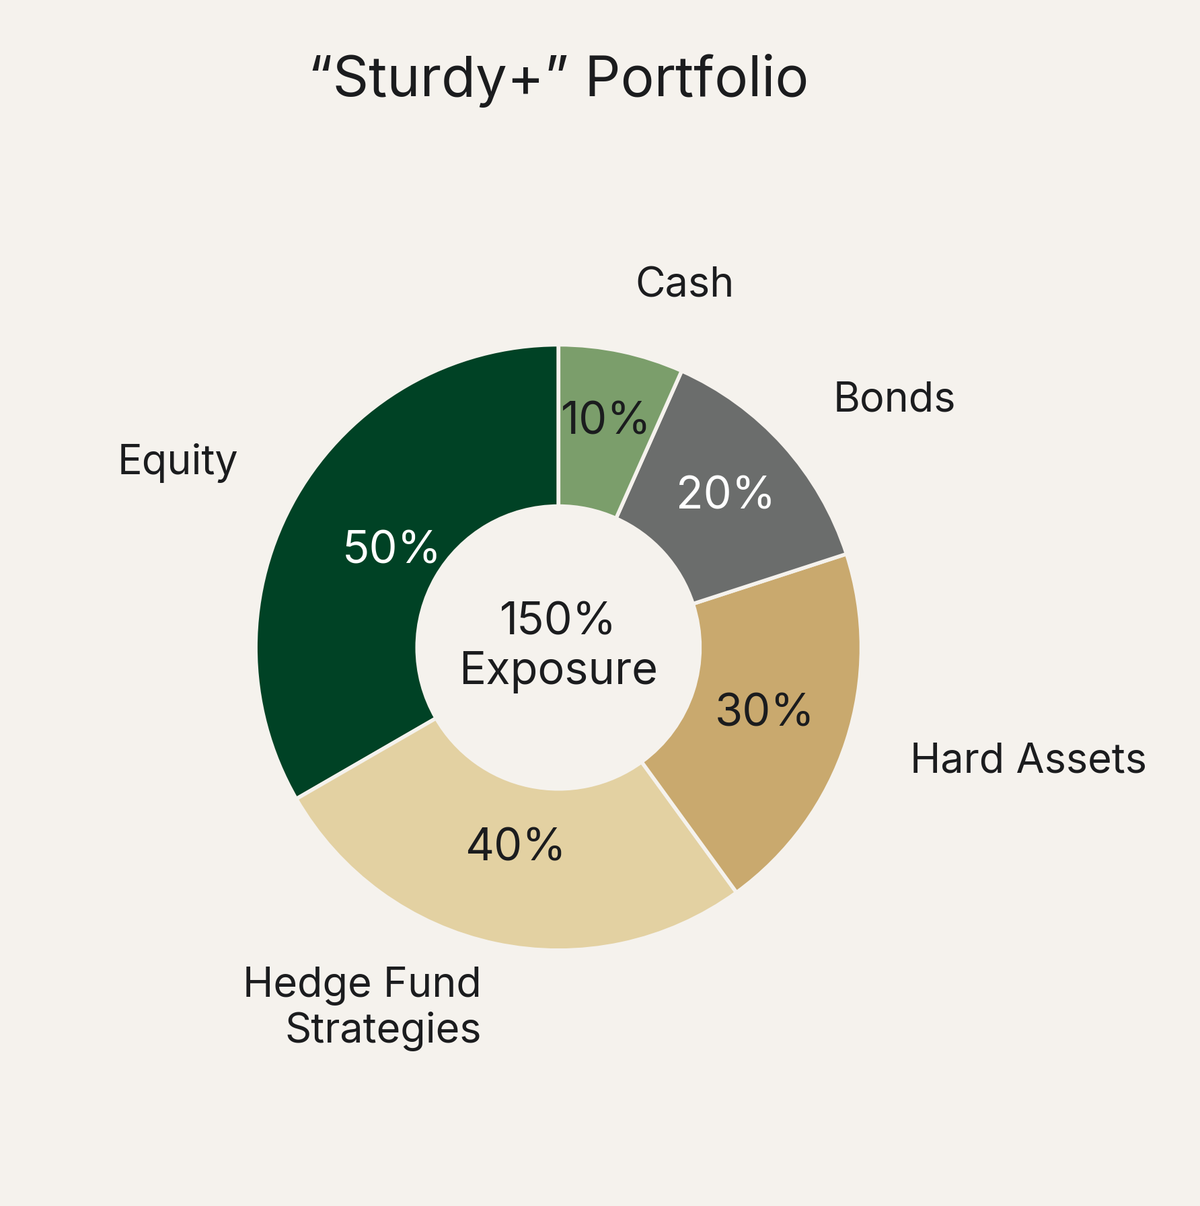
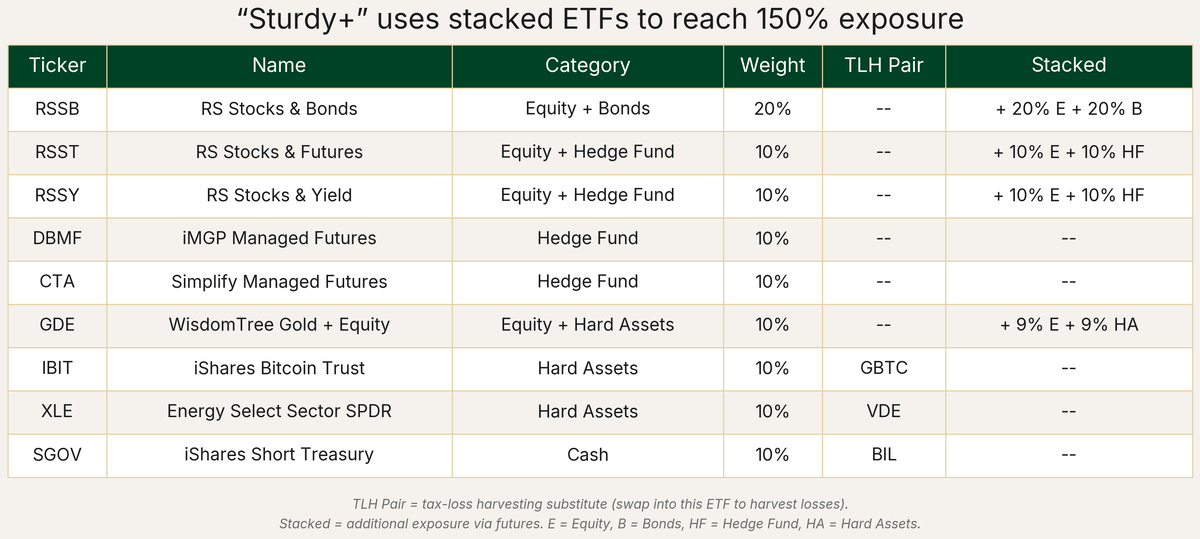
Strategy: 150% total exposure via stacked ETFs (RSSB, RSST, RSSY, GDE). A stacked ETF bundles two exposures into one ticker, so $1 invested gives you exposure to both at once.
Advantages: Capital efficiency (getting more market exposure per dollar invested) lets Sturdy+ reach 150% exposure while only deploying 100% of capital. Broker margin (borrowed money from your brokerage used to buy more securities than your cash balance supports) is not needed, so the investor avoids any risk of margin calls and avoids inflated borrowing rates. Investors simply buy these ETFs like any other, and the stacked exposures are already baked in. Futures-based holdings get 60/40 tax treatment at the fund level (60% long-term, 40% short-term), which passes through to shareholders more tax-efficiently than you might expect for a leveraged strategy.
Disadvantages: More volatile than Sturdy due to the additional exposure. More complex to understand and requires real effort to learn the mechanics. Stacked ETFs are newer products with shorter track records. Requires comfort with leverage and futures, even though the implementation is straightforward.
How the Leverage Works: Four holdings provide stacked exposure:
- RSST (10% of portfolio) = 10% US equity + 10% hedge fund strategies (trend following: a strategy that buys assets going up and sells assets going down)
- RSSY (10% of portfolio) = 10% US equity + 10% hedge fund strategies (carry: earning the yield difference between holding an asset and financing it)
- RSSB (20% of portfolio) = 20% global equity + 20% bonds
- GDE (10% of portfolio) = 9% US equity + 9% gold
Think of stacked ETFs like combination drugs: Augmentin gives you amoxicillin plus clavulanate in one pill. RSST gives you S&P 500 plus hedge fund strategies in one ticker. Combined with the standalone holdings (DBMF, CTA, IBIT, XLE, SGOV), total exposure reaches approximately 150% while only deploying 100% of capital.
Tax-Advantaged Tweak: Investors typically prefer holding SGOV in tax-advantaged accounts (Roth, 401(k), 403(b)). Bond interest is taxed at ordinary income and benefits more than the other ETFs from sheltering in tax-advantaged vehicles.
What Changed
Rebalanced to target. XLE had grown to 13.4% of Sturdy+ against a 10% target, 34% over and past its band. RSSY was close behind at 12.1%. The whole portfolio reset to target at the October 23 close. The main trades, as a share of the portfolio:
- Trimmed XLE (13.4% to 10%), RSSY (12.1% to 10%), and RSST (10.5% to 10%)
- Added to IBIT (7.9% to 10%), RSSB (18.4% to 20%), GDE (8.6% to 10%), and SGOV (8.8% to 10%)
Sturdy+ gained 1.1% since our September update and leads at +14.4% YTD. XLE (+8%), CTA (+7%), and DBMF (+6%) led, while RSSB fell 4% as international stocks dropped and GDE fell 9% as gold slid.
Tax Loss Harvesting Opportunities
- IBIT (iShares Bitcoin Trust): an unrealized loss of about 10% from its January add price. The substitute is GBTC. As in Sturdy, some investors who plan to harvest use GBTC for the rebalance purchase.
GDE slipped about 1% below its add price, too small to be worth harvesting. Everything else in Sturdy+ is above its add price.
Methodology
These model portfolios track a hypothetical investment made on January 2, 2026. All prices use adjusted close from Tiingo (accounts for splits and dividends). No transaction costs, slippage, or taxes are modeled. Benchmarks: SPY (S&P 500 ETF) and AOR (iShares Core Growth Allocation ETF, a 60/40 proxy). All metrics annualized where applicable. Rebalancing follows a quarterly 5/25 band check; the October 2026 rebalance is modeled at the October 23 close.
The portfolios are account-agnostic. They work in taxable, traditional IRA, Roth IRA, 401(k), or any other account type. Tax-advantaged tweaks are noted per portfolio as suggestions, not requirements.